Smart agency banking.
The problem
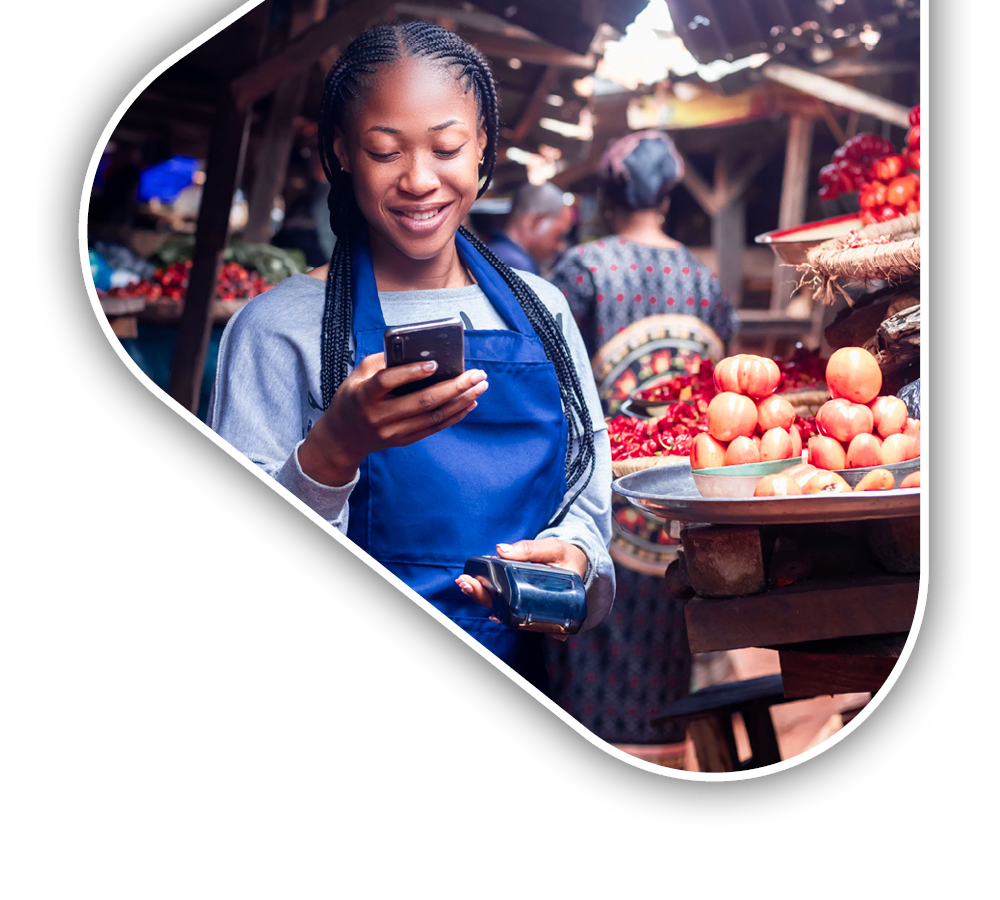
Branches are expensive and cannot reach rural or underserved customers.
Who it's for
Banks, MFIs and mobile money providers in emerging markets.
Benefits
Banking close to where people live and work
Convenient access
Customers bank with local agents near their homes or workplaces, at times and places that suit them.
Lower costs
An agent network costs less to run than physical branches.
Financial inclusion
Reach rural communities and low-income households that branches cannot serve.
Customer growth
Attract people who have not used banking services before.
Customer relationships
Agents give personal help, which builds trust and loyalty.
Market expansion and data
Enter remote markets, and use agent interactions to inform decisions.
How it works
Agents act as extensions of your bank
- 1
Authorised agents
Banks work with authorised third-party agents, individuals or businesses acting as extensions of the bank.
- 2
Everyday transactions
Agents handle deposits, withdrawals, transfers, loan repayments and bill and utility payments.
- 3
Digital tools
Agents process transactions on digital platforms and tools provided by the bank.
- 4
Real-time oversight
The bank monitors activity in real time on a central platform, on secure, encrypted systems.
Take your bank to where your customers are
Tell us about your market and agent model and we will suggest where to start.